


The Importance of Proper Valuation
INTERVIEWER As part of Prime Minister Abe Shinzō’s growth strategy, his administration has come up with the Corporate Governance Code and Stewardship Code, which aim to strengthen investor oversight of companies. Do you see these codes as having an effect in practical terms?
MURAKAMI I think that they are having an effect and that their impact will increase as time goes by. The only major problem with the Japanese market versus the US market is the high level of retained earnings at Japanese companies. If you look at ROE [return on equity], the figure for Japan is only about 7%, against 15% for the United States. And the reason for this big difference is the size of companies’ retained earnings. If these internal reserves were slashed, the Japanese figure would become comparable to what we see in the United States. Most of the companies that have especially large levels of internal reserves are ones with cross-held shares. Almost all of the companies with P/B ratios like 0.4 or 0.5 have net cash exceeding market capitalization, along with substantial real estate holdings and cross-held shares.
The appropriate level of risk weight for companies to hold should be statistically evident in the wake of events like the Lehman shock [the crisis following the collapse of Lehman Brothers in September 2008] and the Great East Japan Earthquake [March 2011], but it seems to me that many Japanese companies have failed to address this issue.

The system of raising funds through direct financing presupposes the existence of proper share prices. But today’s Japanese corporations are failing completely in this respect. Meanwhile, the problem with the Japanese economy as a whole is that nobody is borrowing money from banks. The money supply is growing, but the funds aren’t making it out into the market. This is because companies are hanging on to such high levels of internal reserves.
If businesses don’t take out loans from banks, the banks can’t make profits. Lending is like the blood supply for the economy. If funds are circulating, they boost economic activity. Management at listed companies needs to calculate appropriate risk-weighting levels and raise funds accordingly.
Put Cash to Work and Aim for Higher Share Prices
INTERVIEWER With the spread of sound corporate governance, will calls from shareholders be able to change the status quo, where companies are sitting on cash rather than investing it?
MURAKAMI It’s been a bit over a year and a half since the Stewardship Code was introduced and just half a year since the Corporate Governance Code was launched, but the effects have already been dramatic. Foreign activist funds have also stepped up their involvement in Japan. So I’m confident that the investment environment will change.
INTERVIEWER You earlier referred to raising capital efficiency as the measure of corporate excellence. Can you give some examples of companies or CEOs that meet this test?
MURAKAMI A firm like SoftBank that takes on challenges and produces results is a good company. Tackling challenges means, for example, using internal reserves to make investments or leveraging capital in pursuit of higher profits. In practice, companies that do this enjoy rising stock prices and growth in scale, so CEOs that take this sort of approach are the ones we like to support as investors.
In Her Father’s Footsteps
INTERVIEWER Your father closed down his Murakami fund in 2006, and over the decade since then the world has seen major changes, including the Lehman shock and the March 11 disasters. How do you feel about constantly being talked about and interviewed in terms of how you compare with your father?
MURAKAMI I think the media basically wants to talk to my father and get his comments, not mine. I’m grateful for the attention my father brings to our company. And I think this is why I get opportunities to talk about corporate governance.
INTERVIEWER Your father accomplished some major undertakings [as head of the Murakami fund], such as the merger of the Hankyū and Hanshin railway companies. What sort of impression did you have of him at the time?
MURAKAMI I was in high school at that point, so I really didn’t understand anything about my father’s activities. I was going to school in Switzerland, so I wasn’t exposed to the Japanese media either. When I saw a TV news story about him on the plane as I was flying back to Japan, it came as quite a surprise. Then he was arrested; in college I had the experience of people giving me nasty looks and gossiping about me, which made me feel a certain amount of resentment toward him.
Now that I’m working in the same field as my father, my assessment is that he was quite correct in his stance regarding the proper shape and governance of listed companies.
INTERVIEWER I would think that in most cases someone whose father was arrested would want to follow a different career path. What motivated you to carry on with his work?
MURAKAMI My father’s arrest motivated me to investigate whether he had really done wrong. I decided to look for a job in the world of finance when I graduated from college and, after a few years, to leave that job and try working alongside him as a fund operator.
Another consideration was that the task of spreading the practice of good corporate governance among Japanese companies hadn’t been completed in my father’s time [with the Murakami fund]. Japan’s listed companies are still only partway there. If they properly undertake to build up their stock prices, it will ultimately benefit Japan as a whole and promote the country’s economic development. I decided that I wanted to help out in the process of reaching this goal.
Satisfaction for All Stakeholders
INTERVIEWER What’s your next objective?
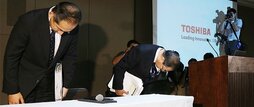
MURAKAMI As I see it, there are two sides to corporate governance. One side is to avoid violations of the rules, such as those we’ve seen at Toshiba and at Kuroda Electric. This means governance directed at compliance with laws and regulations and strict observance of relevant rules. The other side is for CEOs to work toward achieving proper pricing of their companies’ stocks in keeping with the Corporate Governance Code.
I think our company is the only fund that’s currently addressing the aspect of compliance violations. Whistleblowers emerged at both Toshiba and Olympus, and I would say that this reflects the fact that CEOs of listed companies have been failing to follow the rules. At C&I, in addition to pushing for proper stock price formation, we intend to work toward having every listed company implement proper legal compliance and achieve satisfaction for its various stakeholders, including employees.
(Based on a September 7, 2015, interview in Japanese.)



 Read in other languages